2026 Class 8 Mathematics · English Version · Chapter 2 · Chapter companion part
Chapter 2D: Statements, repayments and mixed written problems
Read a fictional statement, follow transaction timing and solve multi-stage profit problems with explicit assumptions.
About this lesson and its coverage
Class 8 English Version: part D of the chapter 2 companion. Eight teaching sections, 30 written tasks and a notebook challenge. Selected companion coverage, not complete textbook coverage; use all four parts and ask a teacher to review explanations and open solutions.
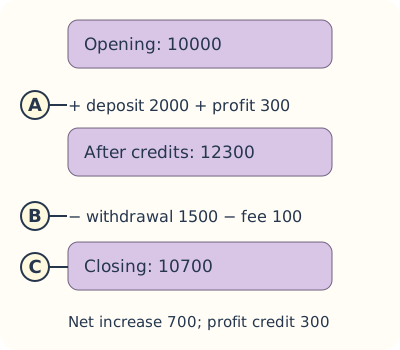
A statement records an opening balance, dated descriptions, money in (credits), money out (debits) and a running balance. In the fictional table, start with 10000, add deposit 2000 and profit credit 300, then subtract withdrawal 1500 and fee 100. Closing balance is 10700. The 700 net increase is not all profit: deposits and withdrawals also changed the balance.
Reconcile, then isolate profit
Closing = opening + credits − debits. Separate a new deposit from a profit credit; a withdrawal is not automatically a loss from an investment. The fictional statement credits 300 profit, but that alone does not establish an annual rate without the balance history, period and calculation terms. A fee reduces the displayed balance; do not silently omit it.
A payout is different from reinvestment
At 8% simple annual rate, a principal of 80000 earns 80000 × 0.08 × 3/12 = 1600 in the first three months. Four equal quarterly payouts total 6400 for a year if the principal stays 80000. If these payouts leave the account, they do not themselves earn compound profit there. A stated term of several years does not mean the first payout uses all those years.
Apply a repayment after the stated interest
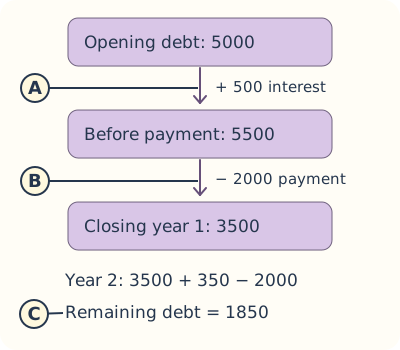
For an invented loan of 5000 at 10% yearly, with 2000 repaid at each year end after interest: first add 500 to reach 5500, then subtract 2000 to leave 3500. Next year add 350 to reach 3850 and repay 2000, leaving 1850. Subtracting the repayment before charging that year’s interest gives a different model. Always state timing.
Weight rates by the money they apply to
For equal one-year periods, 3000 at 10% earns 300, while 2000 at 5% earns 100. Total profit 400 on total principal 5000 gives 8%. The unweighted average 7.5% ignores the unequal principals. The 8% measures total one-year simple profit per 100 of combined initial principal; it is not a guaranteed future return.
Unequal durations share a rate, not a time
For a shared simple rate r, two amounts satisfy total profit I = r(P1t1 + P2t2). With 2000 for two years and 3000 for three years, the weighted time-principal total is 4000 + 9000 = 13000 taka-years. If total profit is 1300, r = 0.10 = 10% annually. Do not add the years and apply that sum to all of the money.
Split a one-year total between two rates
Let x + y = 10000 and annual simple profit be 0.08x + 0.04y = 600. Substitute y = 10000 − x to get 0.04x + 400 = 600; x = 5000 and y = 5000. The source mixed-loan example uses one-year interest in its solution although the opening wording does not state that duration explicitly. Our version states one year and checks both equations.
Audit a written solution rather than its final line
Compound example 5 on printed 26 writes 61740 − 5600 but reports 5740. Its original principal is 56000, so the consistent subtraction is 61740 − 56000 = 5740; the printed subtraction has a missing zero. Check inputs, units, timing, operations and the final balance. A correct-looking final number does not make every intermediate step correct.
Worked example
In the fictional statement, total money in is 2300 and total money out is 1600. The balance rises by 700, while the profit-credit row is only 300. Reconciliation explains the difference without inventing an annual rate.
Identify cost or principal, rate, time and the requested quantity; state units and the calculation model.
Convert percentage numbers to decimals and months to years; show substitutions and intermediate steps.
Check the balance or reverse calculation. Write a plain number for a numeric check; show reasoning on paper for review.
Statement extension is clearly labelled
The chapter names understanding bank statements as an outcome but does not supply a statement facsimile. Kidemy’s invented table teaches that outcome; it is not a real customer record or bank document.
A source answer key is a check, not proof
The saved answer page 188 gives selected exercise results. We independently recompute our fresh tasks and retain missing-condition notes where the printed question cannot determine a unique answer.
Equal quantities require an equal-quantity average
In Exercise 2.1(19), the two unit costs are 36/12 = Tk 3 and 36/18 = Tk 2. Equal numbers of bananas make average cost (3 + 2)/2 = Tk 2.50 each. Sale at 36/15 = Tk 2.40 loses Tk 0.10 per banana, or 0.10/2.50 × 100 = 4% of cost. A total cash loss needs the quantity bought. For 25% profit, four bananas cost Tk 10 and should sell for Tk 12.50. Do not average the pieces-per-taka rates.
Fictional statement: follow the running balance
Invented classroom data, not a real bank statement. A dash means no entry, not missing balance data.
Fictional statement: follow the running balance
Date / description
Credit (Tk)
Debit (Tk)
Balance (Tk)
1 Jun · opening
—
—
10000
2 Jun · new deposit
2000
—
12000
30 Jun · profit credit
300
—
12300
30 Jun · withdrawal
—
1500
10800
30 Jun · fee
—
100
10700
Read across each row in the displayed order. Total credits 2300 minus total debits 1600 gives net increase 700; only 300 is labelled profit. No annual rate can be inferred from this table alone.
Repayment after interest: a two-year ledger
Invented loan 5000 at 10% annually; repay 2000 at each year end after charging that year’s interest.
Repayment after interest: a two-year ledger
Year
Opening (Tk)
Interest (Tk)
Before payment (Tk)
Payment (Tk)
Closing (Tk)
1
5000
500
5500
2000
3500
2
3500
350
3850
2000
1850
Row two opens with row one’s closing debt. This arithmetic assumes no fees, new borrowing or other transactions. Check the stated order before calculating.
Weight an annual rate by its principal
Invented one-year simple-profit contributions; both investments last exactly one year.
Weight an annual rate by its principal
Principal (Tk)
Annual rate
Year profit (Tk)
3000
10%
300
2000
5%
100
Total 5000
Combined 8%
Total 400
The combined 8% means 400 simple profit on 5000 in this one-year example. It is not the unweighted 7.5% average and not a future-return promise.
Debt just after this / the previous year-end payment.
r
Decimal annual loan rate.
Dk
Payment made after year k’s interest, in taka.
credits / debits
Money into / out of a deposit account, respectively.
Statement: 10000 + 2300 − 1600 = 10700.
Loan year one: 5000 × 1.10 − 2000 = 3500.
Loan year two: 3500 × 1.10 − 2000 = 1850.
Check each row against the preceding closing balance.
Account reconciliation and a loan recurrence describe different ledgers. A payment before interest requires a different ordering; stop and clarify an unstated schedule.
Solve a weighted or split-rate simple problem
State time explicitly: the split-rate example below lasts one year.
Shared r = I/(P1t1 + P2t2)
x + y = T
r1x + r2y = I (one year)
One-year split: x + y = 10000 and 0.08x + 0.04y = 600.
Substitute y = 10000 − x to get 0.04x = 200, so x = y = 5000; verify 400 + 200 = 600.
Unequal periods require their own time factors. A split-rate task without a duration cannot automatically use the one-year equation.
Explore the mathematical figures
Match each letter to its explanation. Read the quantities, units and relationships, then check the counts or equations. These are original teaching models.
Interest first, repayment second
Read operations from top to bottom. Changing the payment order changes which money earns that year’s interest.
A · Interest on the opening debt
First-year interest is 500; second-year interest is 350 because the debt changed.
B · Payment after interest
Subtract 2000 after each year’s interest, as specified.
C · Debt still owed
1850 remains after two payments; it is not total interest or the amount repaid.
Original invented loan example, not lending terms. Box sizes are schematic; all money amounts are explicitly labelled.
Explore the mathematical figures
Match each letter to its explanation. Read the quantities, units and relationships, then check the counts or equations. These are original teaching models.
Separate profit from the net balance change
Match the flow with the fictional semantic statement table and check each running balance. A net increase alone does not identify profit.
A · Credits are money in
Deposit 2000 and profit 300 together add 2300; they are different kinds of credit.
B · Debits are money out
Withdrawal 1500 and fee 100 together subtract 1600.
C · Closing balance
10700 is 700 above opening, but only the 300 credit is labelled profit.
Original invented statement extension for the chapter’s fourth outcome. No customer data, real bank document or implied annual rate.
Your written practice
Show your working on paper. Check your answer, then choose Next.
Show model answer and explanation
300
Read the profit row, not the total net balance change.
Show model answer and explanation
10700
10000 + 2000 + 300 − 1500 − 100 = 10700.
Show model answer and explanation
5000
5320 − 400 + 80 = 5000.
Show model answer and explanation
1600
80000 × 0.08 × 0.25 = 1600.
Show model answer and explanation
6400
4 × 1600 = 6400; no reinvestment is assumed.
Show model answer and explanation
3500
5000 × 1.10 − 2000 = 3500.
Show model answer and explanation
1850
3500 × 1.10 − 2000 = 1850.
Show model answer and explanation
8
(300 + 100)/5000 × 100 = 8.
Show model answer and explanation
10
1300/(2000 × 2 + 3000 × 3) × 100 = 10.
Show model answer and explanation
5000
0.08x + 0.04(10000 − x) = 600 gives x = 5000.
Show model answer and explanation
5000
10000 − 5000 = 5000.
Show model answer and explanation
11025
10000 × 1.05² = 11025.
Show model answer and explanation
debit
The debit column records money out.
Show model answer and explanation
700
10700 − 10000 = 700; this need not equal profit.
Show model answer and explanation
3850
3500 × 1.10 = 3850, provided no other transactions or fees occur.
Write in your own words. A guardian or teacher should review this response.
Show model answer and explanation
Opening 10000 → deposit 12000 → profit credit 12300 → withdrawal 10800 → fee 10700. Credits total 2300 and debits total 1600.
Check each running balance, labels and the final reconciliation.
Write in your own words. A guardian or teacher should review this response.
Show model answer and explanation
It includes a 2000 deposit, a 300 profit credit, a 1500 withdrawal and a 100 fee. Net change is 700 but the labelled profit credit is 300.
Separate cash flows from earnings.
Write in your own words. A guardian or teacher should review this response.
Show model answer and explanation
A debit is outflow. Closing = 4000 − 500 + 200 = 3700.
Explain the direction of both entries.
Write in your own words. A guardian or teacher should review this response.
Show model answer and explanation
No. The calculation period, eligible balance history and account terms are also needed. A new deposit or withdrawal may change the relevant balance.
Do not invent a guaranteed rate from one credit.
Write in your own words. A guardian or teacher should review this response.
Show model answer and explanation
The first quarter is 0.25 year, so payout = 120000 × 0.06 × 0.25 = 1800. Five years describes the overall term, not this first payout period.
Keep annual rate and elapsed time distinct.
Write in your own words. A guardian or teacher should review this response.
Show model answer and explanation
Four withdrawn 200 payouts total 800, leaving principal 10000. Reinvestment at 2% quarterly gives 10000 × 1.02⁴ = 10824.3216, or 10824.32 rounded at the end.
Name the nominal-rate convention, final rounding and different cash flows.
Write in your own words. A guardian or teacher should review this response.
Require the order and all balances, not only the final debt.
Write in your own words. A guardian or teacher should review this response.
Show model answer and explanation
The stated model gives 5000 × 1.10 − 2000 = 3500. Paying first would give (5000 − 2000) × 1.10 = 3300; it changes transaction timing.
Show both conditional results and use the specified one.
Write in your own words. A guardian or teacher should review this response.
Show model answer and explanation
Profits are 360 and 360. Combined 720 on 10000 gives 7.2%. It is weighted by principal, not the simple mean 7.5%.
State the equal one-year period and what 7.2% measures.
Write in your own words. A guardian or teacher should review this response.
Show model answer and explanation
r = 2080/(4000 × 2 + 6000 × 3) = 2080/26000 = 0.08, or 8%.
Check each loan’s profit and their sum.
Write in your own words. A guardian or teacher should review this response.
Show model answer and explanation
x + y = 20000 and 0.08x + 0.05y = 1300. Substitution gives 0.03x = 300, so x = 10000 and y = 10000; check 800 + 500.
Both the total principal and profit equations must hold.
Write in your own words. A guardian or teacher should review this response.
Show model answer and explanation
The split earns 1300 in one year. The all-at-6% simple alternative earns 1200 in one year. The separate two-year compound scenario gives amount 22472 and profit 2472. Periods differ, so these are calculations under different conditions, not a ranking of actual offers.
Label each time period and avoid comparing unlike amounts as identical offers.
Write in your own words. A guardian or teacher should review this response.
Show model answer and explanation
The consistent operation is 61740 − 56000 = 5740. Subtracting 5600 would instead give 56140. The printed intermediate subtraction is missing a zero.
Mention the printed error and verify both subtractions.
Write in your own words. A guardian or teacher should review this response.
Show model answer and explanation
For example, an amount and annual rate alone do not determine principal. Add a duration, specify simple or compound calculation, and state any transaction timing before solving.
Check that the repaired problem has enough information and a verified answer.
Write in your own words. A guardian or teacher should review this response.
Show model answer and explanation
Choose an opening balance, at least one credit and debit, label all amounts and dates, and check each balance. For example 3000 + 500 − 200 = 3300, not 3700.
Accept different invented data; require a reconciled correction and clear fictional label.
Progress and browser storage
Notebook challenge, sources and further study
Your profits and balance notebook
Create a fictional statement, a repayment ledger and a mixed-rate solution; exchange them for checking.
Review with a guardian or teacher
Label invented data, credit/debit direction, units and transaction timing.
Reconcile every running balance and verify both equations in a split-rate task.
Explain one error, missing condition or comparison limit in complete sentences.
Keep your work on paper or in a local file. This page does not upload it or automatically grade the project.
Chapter companion and further study
This original Kidemy practice follows the topic order of 2026 Class 8 Mathematics · English Version, chapter 2, printed pages 12–28. It does not replace the complete chapter or its practical teaching.
Use all four Profits companions and compare your written methods with the source exercises. This companion teaches the source problem types with fresh values; it is not a reproduction of every printed question.
Statements are fictional classroom examples. Real account terms, fees and rounding can differ. Original companions for all 11 chapter headings are available; independent source exercises and full working still need review.
Teacher-led lessons, schedules and prices for this outline are upcoming. You can use any starter practice above now without booking.
Your next step
Solo practice works without an account. Sign in to save a practice record to your learner profile.
Keep practising
Exact lesson links and related activities are labelled separately. Return-to-course links retain your selected learning path.